SEGVERA TECHNOLOGIES

Financial education for Latinos, in Spanish and without jargon.

Clear lessons, educational models, and calculators to understand your money and start small: small, automatic, and consistent contributions — no jargon, no fear.

SEGVERA is education and technology. Advice, execution, and custody are handled by regulated financial institutions.

Couple studying at home Education first understand before you decide See more ↻

You learn in order: budgeting, saving, debt and credit, and finally investing, with its risk explained. Short lessons in Spanish, with examples from your life. First you understand, then you decide.
Latino family gathered at home Made for Latinos focused on the Latino community in the U.S. See more ↻

This is not translated content: it is created for the Latino community in the U.S., with your examples and your everyday Spanish. When the examples are yours, you feel this really is for you.

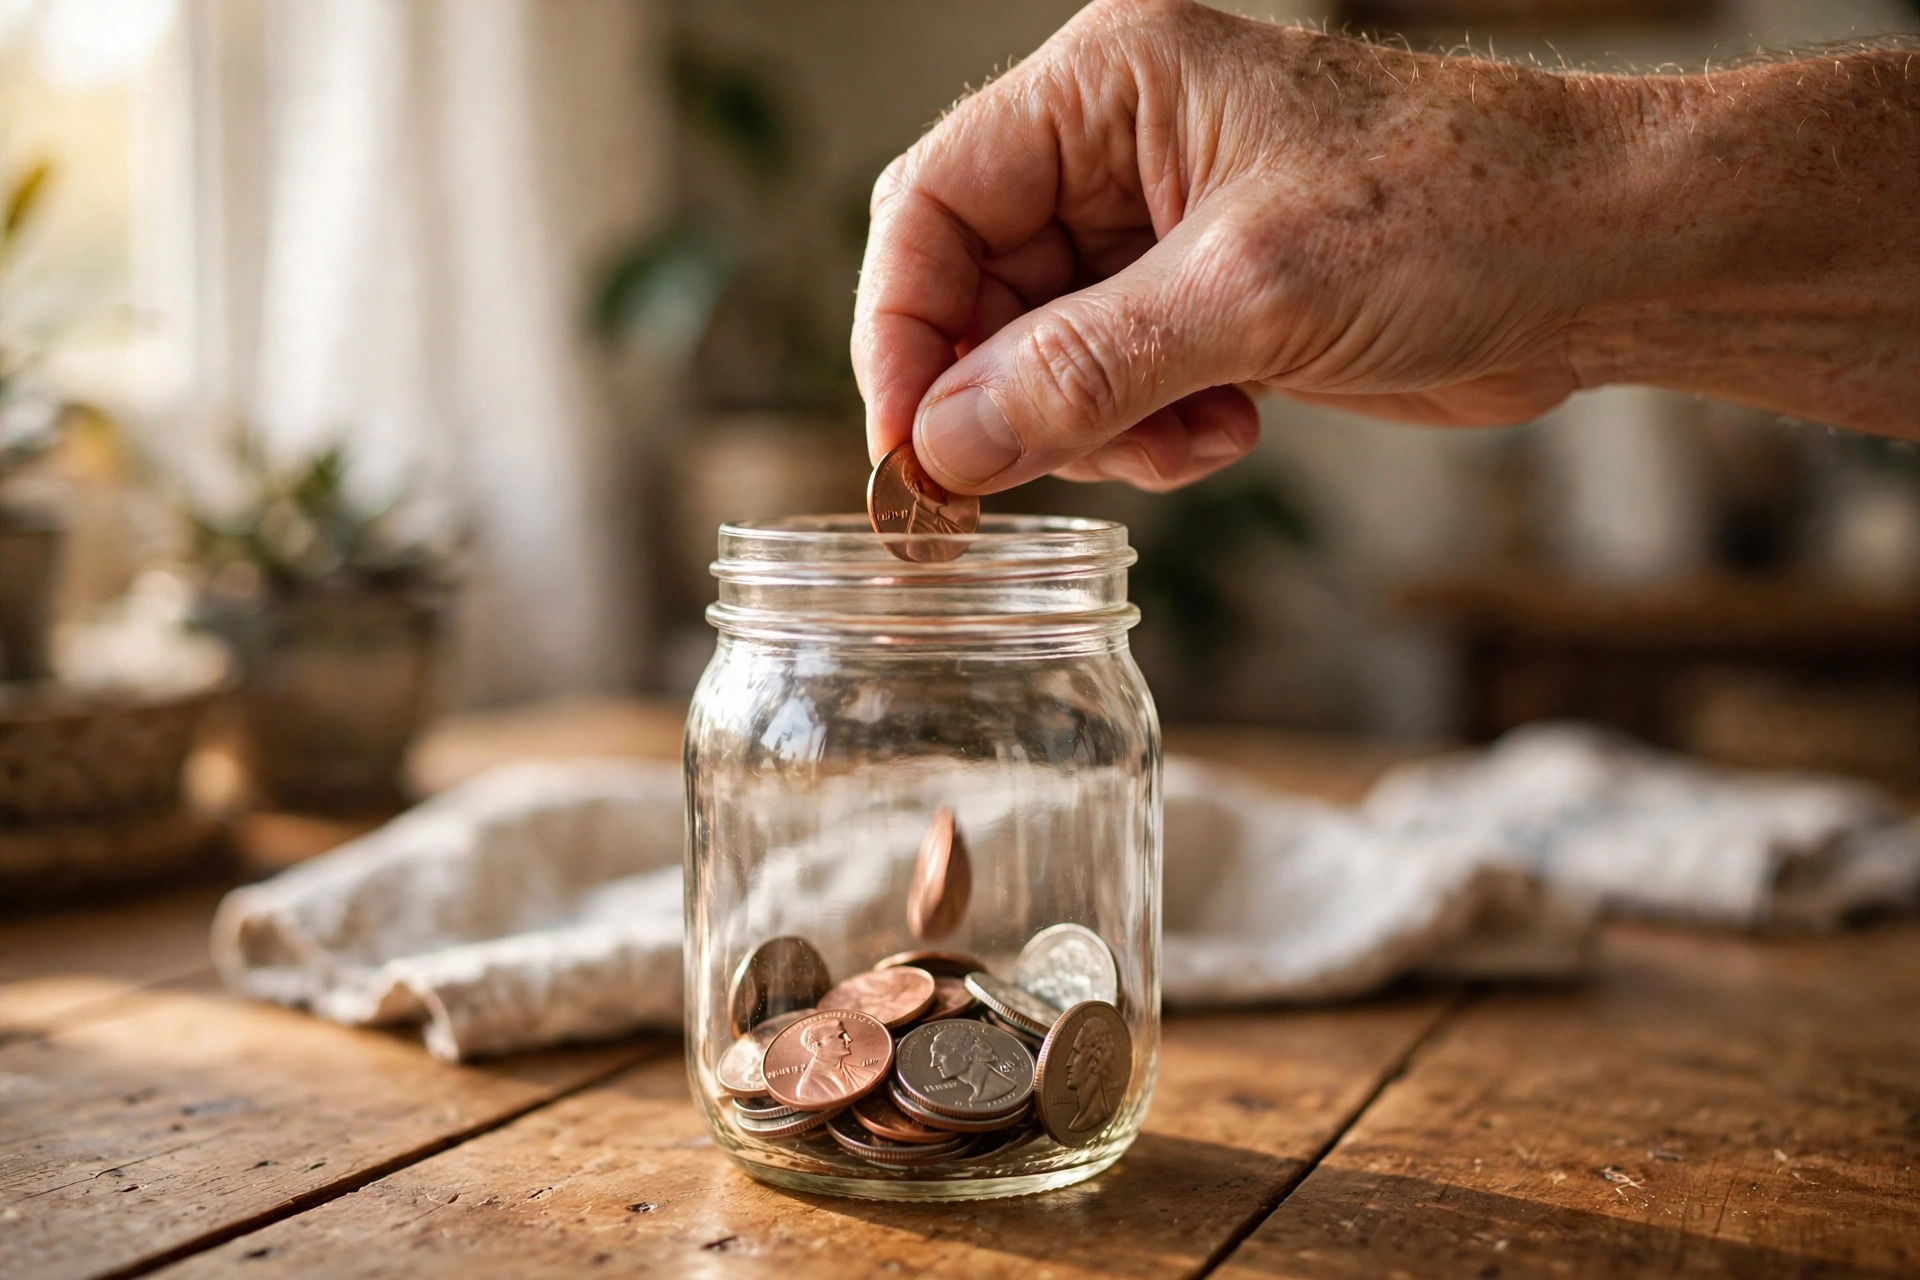
Hand dropping a coin into a savings jar Start small small, consistent contributions See more ↻

Consistency, not the amount: setting aside the same every week, automatically. $25 a week is $1,300 in a year and $13,000 in ten years, just from what you set aside. Small is not small when it is every week.

Hands with a calculator over a budget notebook Tools to practice with calculators and guides with your numbers See more ↻

Educational calculators and guides to practice with your own numbers: budgeting, saving, and the power of setting aside a little every week.

WHAT IS SEGVERA?

A community the traditional system does not serve

Traditional financial advice asks for high minimums and speaks another language — literally. Millions of Latinos in the U.S. build their wealth little by little, with discipline, but without a tool made for them. SEGVERA was created to close that gap: clear education + simple technology + regulated infrastructure.

HOW DOES IT WORK?

The model, in three steps

The model is simple: first you learn, then you understand, and when you decide to invest you do it through regulated financial institutions.

1

Learn

Clear, structured financial fundamentals: budgeting, saving, debt, credit, and investing, explained in an accessible way.

2

Understand

See educational investment models for your profile and time horizon, with illustrative examples and their risks explained.

3

Connect

When you decide to invest, you connect with authorized and regulated financial institutions whose infrastructure executes and holds custody under regulatory supervision.

EDUCATIONAL MODELS

Four ways to think about your money

These models are generic educational examples for understanding how an investment is allocated according to goal and time horizon. They are not personalized recommendations, they do not include return figures, and they are not the portfolios of any product. Tap each one to see the idea and an example.

The idea: protect what you have. It prioritizes stability over growth; ideal for near-term goals (under 2 years) or your peace-of-mind fund.

In practice: most of it in low-movement instruments, such as short-term bonds and cash; a small part in stocks.

Illustrative example: of every $100 → ~$70 in bonds/cash and ~$30 in diversified stocks. Downturns hurt little, but growth is slow too.

The idea: balance. Growing steadily while accepting moderate ups and downs; for medium-term goals (3 to 5 years).

In practice: a balanced mix of bonds that cushion and stocks that push growth.

Illustrative example: of every $100 → ~$50 in bonds and ~$50 in diversified stocks. Neither the calmest nor the riskiest: the middle point.

The idea: seeking the highest long-term growth (over 5 years), accepting sharp drops along the way without panic selling.

In practice: most of it in diversified stocks; bonds play a smaller role. The long horizon is what allows recovery from bad years.

Illustrative example: of every $100 → ~$80 in diversified stocks and ~$20 in bonds. In a bad year it can drop a lot; that is why short-term money never goes here.

The idea: having your money generate regular payments — interest and dividends — instead of only seeking price growth.

In practice: it combines bonds and dividend-paying stocks. Useful to supplement income, for example in retirement.

Illustrative example: of every $100 → ~$60 in bonds and ~$40 in dividend stocks. Payments vary and are not guaranteed: it is also investing, with its risk.

The allocations are simplified educational examples, not real portfolios or advice. Every investment involves risk, including the possible loss of capital.

EDUCATIONAL CALCULATOR

The power of setting aside a little, every week

This calculator is an educational tool — not a product or an account. At the top you see what you yourself can set aside consistently. Below, as a separate hypothetical example, what would happen if that money grew with compound interest at illustrative fixed rates.

In 1 year you set aside$1,300
In 5 years you set aside$6,500
In 10 years you set aside$13,000

Hypothetical example — compound interest over 10 years (illustrative fixed rates):

If it grew at 4% per year* $15,977 You set aside: $13,000 · Example growth: $2,977
If it grew at 7% per year* $18,809 You set aside: $13,000 · Example growth: $5,809

⚠️ Hypothetical example for educational purposes. Markets do not grow in a straight line: there are losing years. This does not predict or promise any result, and it does not represent the return of any product.

The first part is only the sum of what you set aside (52 weeks per year). The scenarios use illustrative fixed rates (4% and 7% per year) only to teach how compound interest works; they are not projections. Investing involves risk, including the possible loss of capital. SEGVERA does not receive or handle user money.

FREQUENTLY ASKED QUESTIONS

What everyone asks

No. What builds the habit is consistency, not the amount: setting aside a small amount every week, without fail, weighs more than starting with a lot once. That is why we talk about $25 a week: in ten years that is $13,000 just from what you set aside, not counting any return.

As a general financial education idea: first a small emergency cushion, then attack high-interest debt, because its interest usually costs more than what that same money would earn saved. This is general information, not a recommendation for your case: each situation is reviewed separately.

When you already have an emergency fund, expensive debts under control, and it is money you will not need in the short term. Investing is for long horizons: markets go up and down, and investing involves risk, including the possible loss of capital.

No. The whole idea of SEGVERA is to start small, with small and consistent amounts. Try the educational calculator above: setting aside $25 a week adds up to $13,000 in ten years, not counting any return.

CONTACT

Let's talk

Institutional partnerships, media, or questions about SEGVERA: write to us.

The button opens your email app with the message already written for info@segvera.com. You send it.

Or directly: info@segvera.com